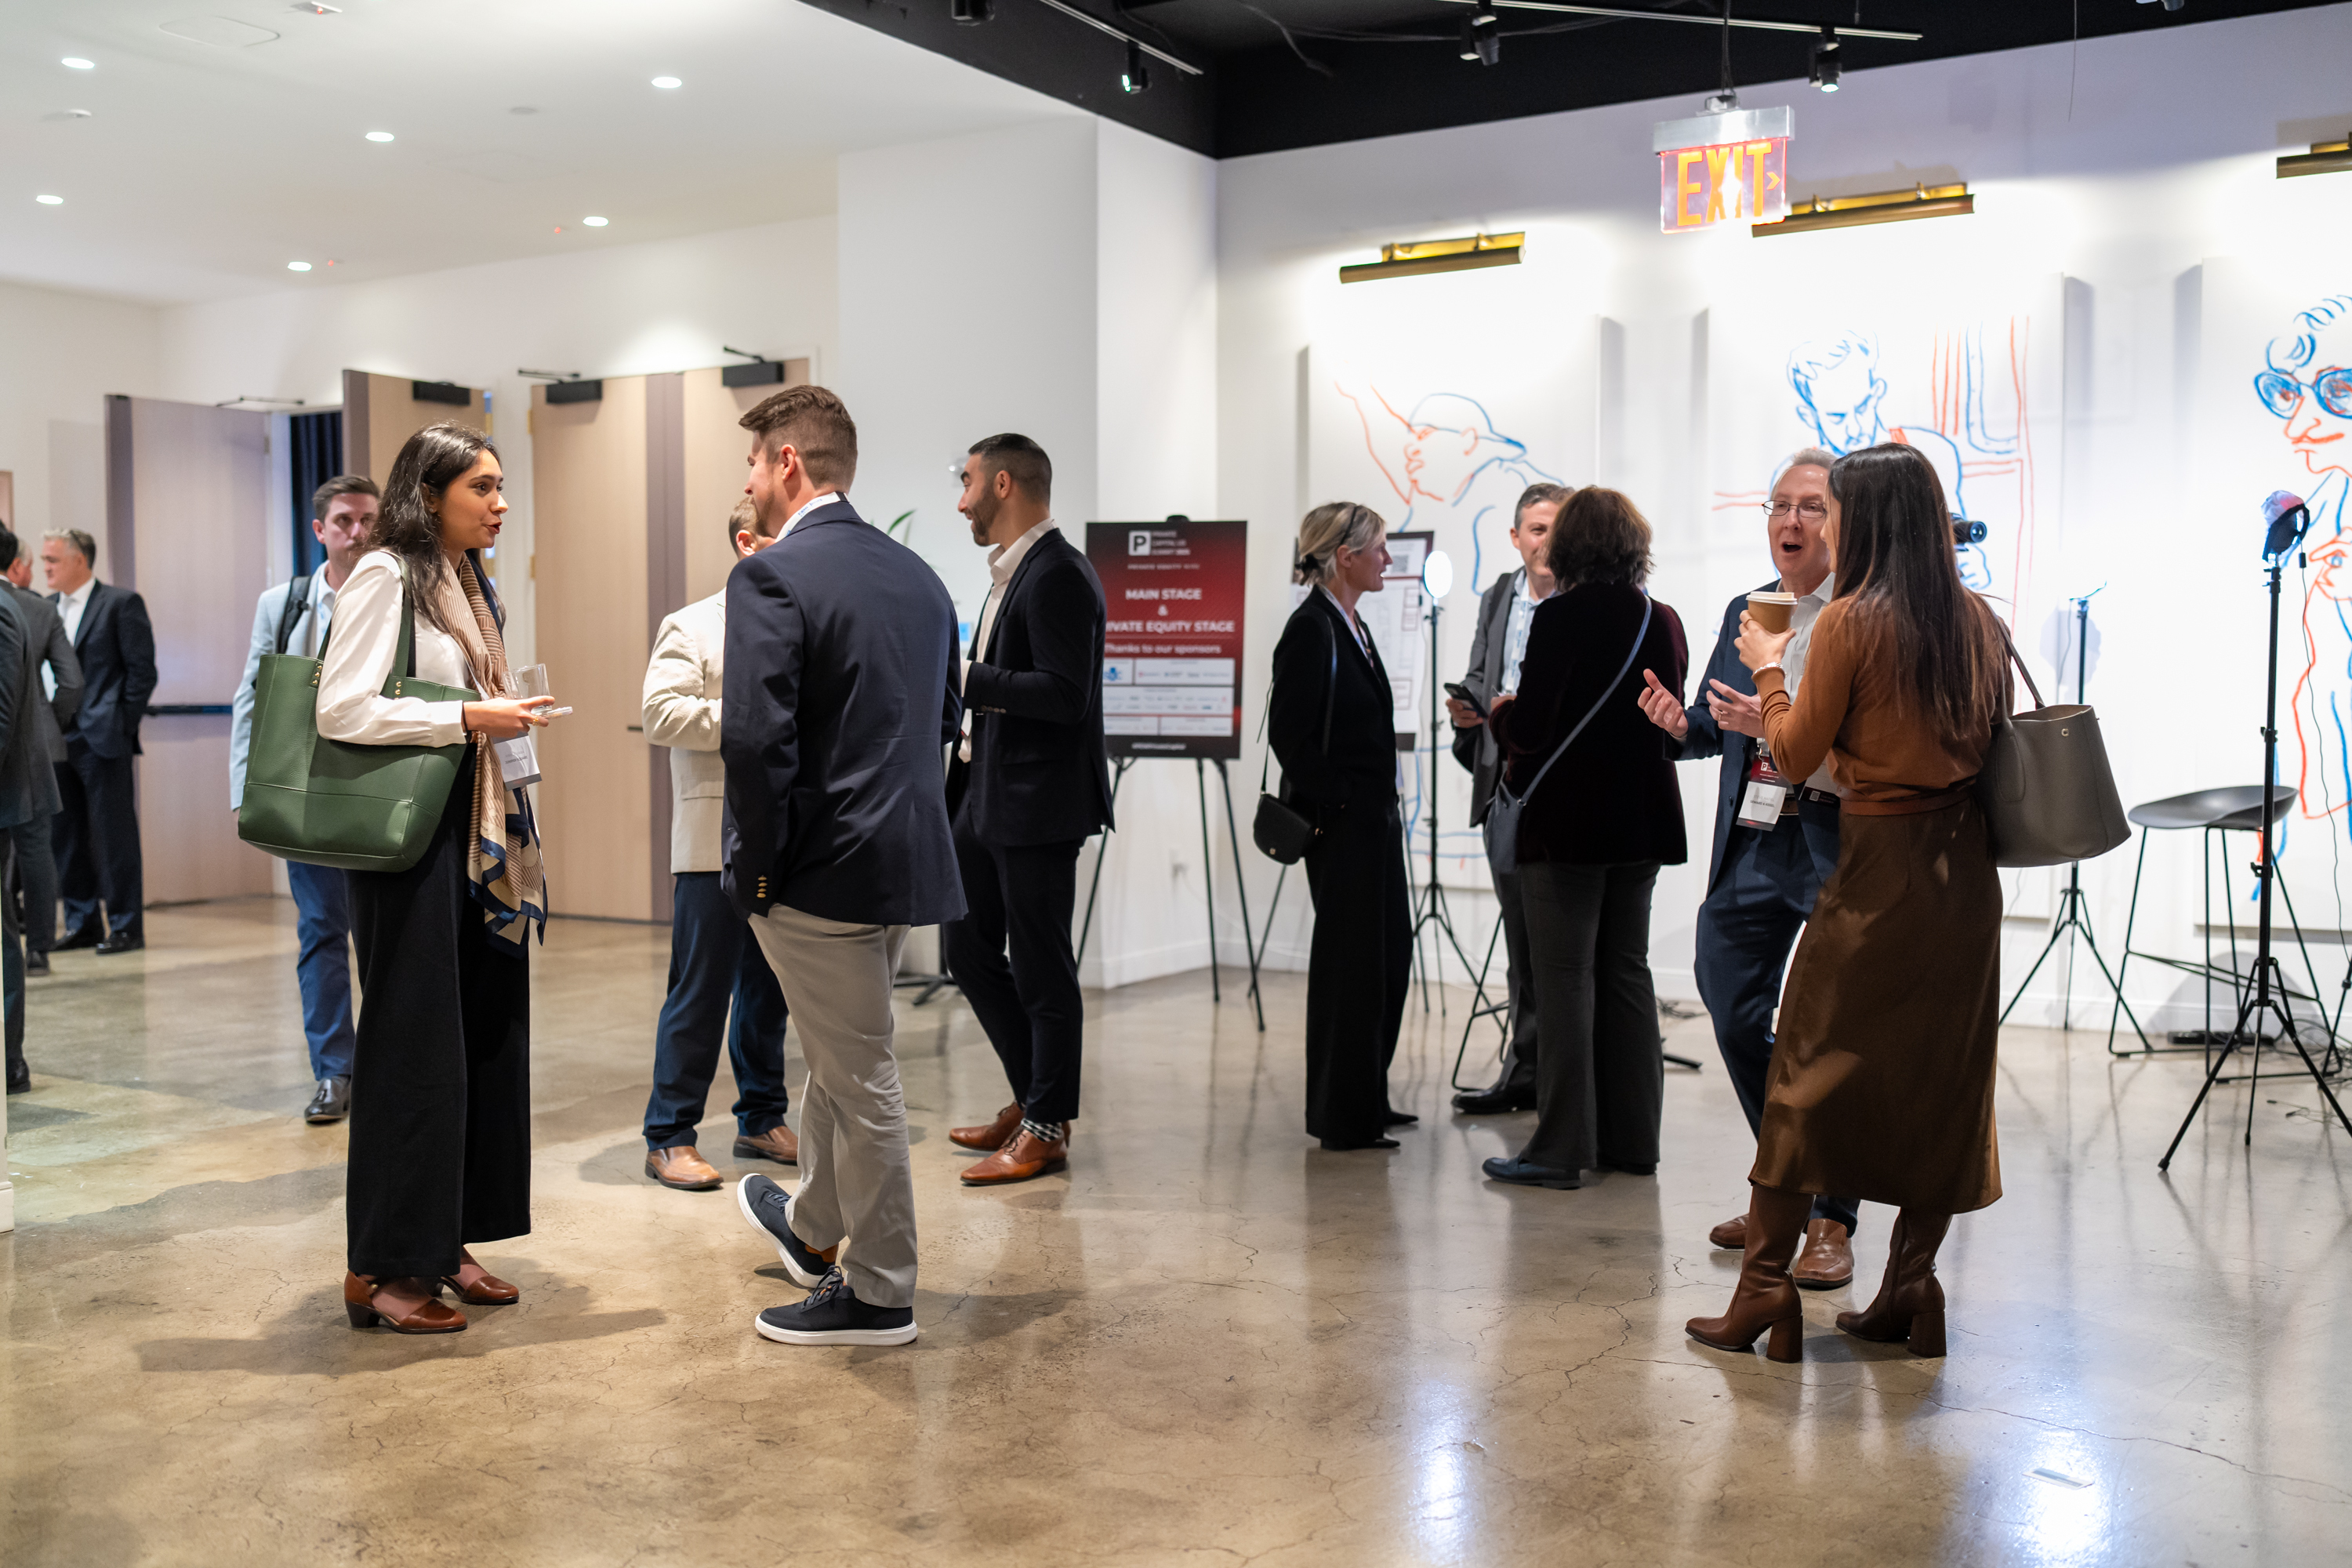
This Thursday, 12 November, the private capital ecosystem convenes at Convene, 237 Park Avenue, for our annual New York Summit – the culmination of a year full of research, insight and analysis.
It has been a year of dispersion. The winners have posted record exits and closed mega funds, while the rest of the market has faced difficult conversations. Redemption waves, continuation vehicle friction and an increasingly selective LP base all point to the same gap: expectations and priorities between investors, managers and their advisers are out of step.
That's the lens for the day. The agenda is curated on the belief that all innovation and product development underway in the industry hinges on greater alignment, and that education is a critical imperative rather than an ancillary talking point. Macro, private credit, secondaries and democratisation will all be examined through it.
Sessions to watch
The morning macro panel. Unpacking the implications of the midterms. We've talked at length about how the political shift will affect data centre spending, and whether regulatory and social friction will have an arresting or a scarcity effect. If the former, the investment case for data centres is under pressure. If the latter, returns could actually see a boost – as pointed out by Jon Gray and reiterated by Blue Owl President Erik Bissonnette.
The evergreens deep dive. The most current trends in evergreens, including evergreen continuation vehicles and umbrella fund structures. Partners Group's move to segment assets within an umbrella evergreen – lower performers pooled in a “distribution” fund, higher performers in a “compounding” one – brings the segmentation debate to the open-ended world. Can investors in private markets structures of all types be sure they're getting access to all the potential upside?
Blue Owl on education and media risk in retail. Few firms have lived the retail story from the inside quite like Blue Owl this year – from becoming a symbol of the redemption wave in private credit to seeing requests ease in recent weeks. Its head of institutional capital has already weighed in on software, disruption and education and media risk, adding nuance to the firm's much-discussed portfolio construction. Our view has been consistent: the quality of disclosures matters more than the frequency. A clear explanation of “semi-liquid” before investment, and visibility into a portfolio's left tail during the term, will do more for stability than any valuation cadence.
The data behind the debate
Our Fundraising and Allocation Index is due shortly, and the bottom line is that LPs are on the diversification charge, but capital is slow to follow into diverse pockets as trust becomes a premium commodity. The queue is long for top-quartile exposure; below that rung, a matchmaking exercise is needed to balance diversification with discipline and performance. Expect these friction points to surface throughout the day.
Join us
We'll have LPs and GPs of all shapes and sizes in the room for a day of alignment and ideation. Places are complimentary for qualifying GPs and LPs – book yours here. I'd be delighted to see faces old and new in New York.
